Germany's €90bn Pension Shift
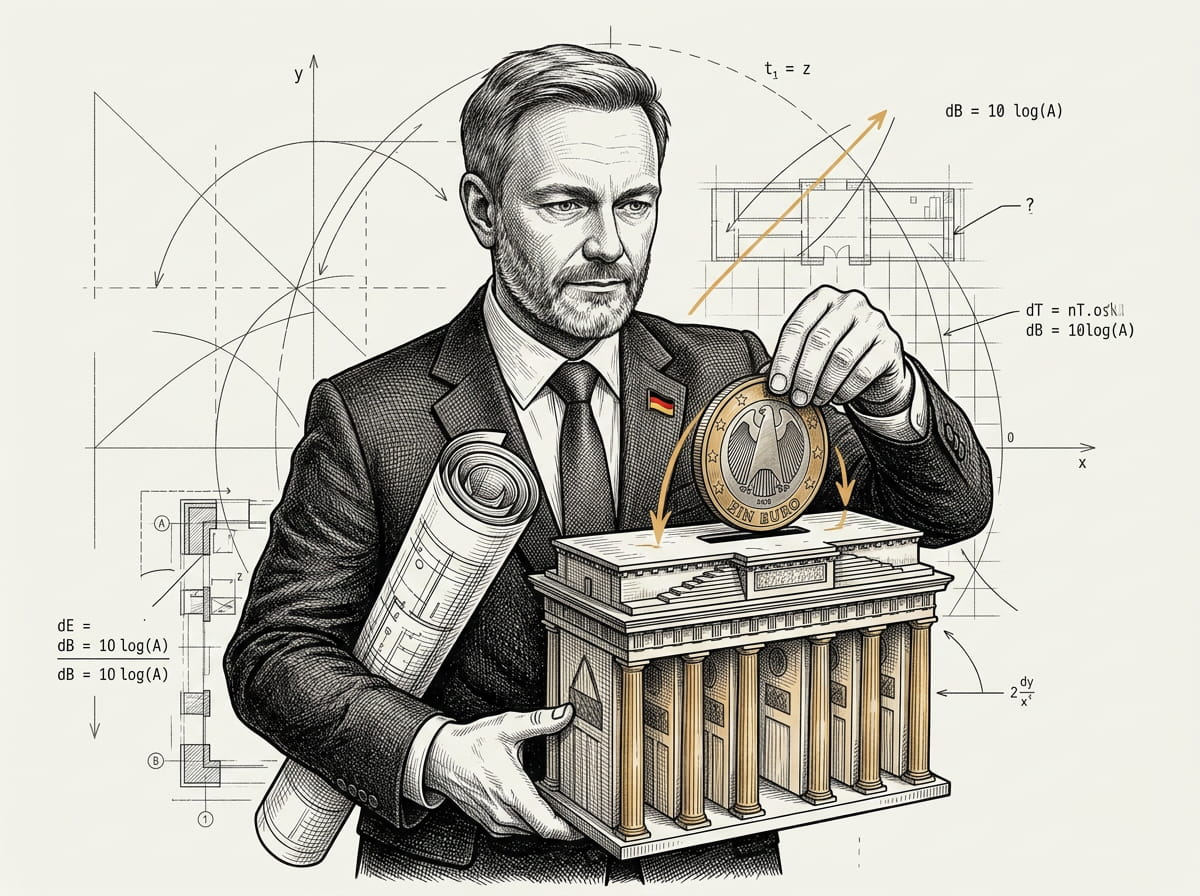
Germany is planning a new national savings plan for pensions that could funnel up to about €90bn a year into markets. The main beneficiaries are likely to be local asset managers and stock exchanges, with retail investing platforms as an added upside.
Germany has the least-funded pension system of any major advanced economy. According to Apollo, funded pension assets are just 7% of GDP, against 149% in Sweden and 185% in Canada. German household wealth sits mostly in deposits. Demographics and the desire for scaled pools of domestic capital are now forcing change.
Pension reform could channel 2% of salaries into long-term savings, 1% from employers and 1% from employees. Phased in from 2028 and completed by 2031, this points to roughly €30 billion a year flowing into Pillar 1. Add parallel reforms to private pensions from 2027 and to occupational schemes, and total inflows could reach around €90 billion annually once fully implemented, roughly 2% of German GDP.
The bottom line is that Germany is starting to build a recurring institutional flow of capital that will deepen German capital markets. Three things to watch: whether workers make voluntary top-ups, whether the public fund manages the money internally or outsources to external managers, and whether occupational coverage broadens beyond the quarter of SMEs it reaches today.
What Drove The Collective Ideas Last Week
Collective Conviction Ideas: Flat WoW
The Conviction ideas were broadly flat last week, with individual stocks rather than a clean sector trade driving the tape. Emerging-market digital platforms and cyclical steelmaking contributed on the upside, the former supported by a falling dollar and the longest emerging-market currency rally since 2007, the latter by firmer nominal growth and commodity pricing. Autonomy and digital-infrastructure exposure also held firm. At the other end, longer-duration growth names felt the pressure of higher bond yields, and those with Asian exposure gave back ground as the oil shock weighed on the region. European industrial-growth and defence names softened, with higher discount rates prompting profit-taking after strong runs. These were directional flags from the macro environment rather than evidence of any change in the underlying investment cases, and no changes were made to the ideas.
Find out more about Collective ideas on CurationAI
Best Content Shared This Week
📚 The Hidden Risk Beneath Private Credit
Why Read? This makes the provocative case that private credit may only be the fuse for a much larger vulnerability sitting inside the US life insurance industry. It examines how insurers use affiliated reinsurance, offshore entities and captive structures to shift liabilities away from their main balance sheets, arguing that some of the capital supposedly backing those obligations may be far less robust than it appears. Read more.
🎧 The AI Riptide
Why Listen? SpaceX's planned $100bn Louisiana buildout provides the starting point for a bigger argument: AI infrastructure could become so attractive that it begins pulling capital away from the rest of the economy, pushing borrowing costs higher for businesses outside the AI stack, before turning to how Figure AI is trying to solve robotics' next bottleneck: real-world training data. Listen here.
Stock Of The Week
When a Major Shareholder Walks Away
Oxford Nanopore has come under pressure after Novo Holdings, the investment arm of the Novo Nordisk Foundation, exited its entire position, taking its voting stake from around 5% to zero. The shares fell roughly 8%, with the market understandably questioning what the departure of a sophisticated life-sciences investor says about the investment case.
The signal, however, is not straightforward. Novo Holdings is undergoing a broader portfolio overhaul, meaning the disposal may say more about its own capital allocation than Oxford Nanopore's fundamentals. It also provides a potential explanation for recent weakness in the shares: a 5% shareholder exiting creates a significant technical overhang regardless of the underlying business.
The key question is what happens now that the block has cleared. If the selling was driven by Novo rather than a deterioration in the thesis, removing a large forced seller could reset the technical picture. Who ultimately absorbed the stake may prove more informative than who sold it.
New or Updated Showcases
Conduit Re
- Conduit Re is a Bermuda-based specialist reinsurer providing cover across property, casualty and speciality markets globally. Built with a clean balance sheet and no legacy liabilities, the business is positioned to deploy capital into attractive reinsurance markets while benefiting from disciplined underwriting, diversified risk exposure and investment income on its growing asset base. Read more.
Phoenix Copper
- Phoenix Copper is an AIM-listed mining developer focused on the Empire Mine in Idaho, a brownfield copper, gold and silver project progressing toward development and production. With an updated prefeasibility study and resource estimate underway, the investment case centres on advancing Empire through engineering, permitting and financing at a time when copper and precious-metal prices strengthen the economics of bringing new US-based supply online. Read more.